My first US credit card with no credit history: rejected, then a secured card, then an offer from the bank that said no
· 6 min read
In the US, almost everything checks your credit: renting an apartment, a phone plan, car insurance, sometimes even a job. When you arrive, you have no credit at all. Not bad credit. No credit. And to the system, that looks almost the same as bad credit.
This is how I got my first credit card, and how fast things changed after that.
My timeline
- July 3, 2026: I arrived in the US
- Late August: My Social Security card arrived
- August 25: I opened my first personal bank account
- August 27: I applied for a Capital One card. Rejected in seconds
- August 28: I applied for the OpenSky secured card
- September 10: OpenSky approved after the third document upload, $750 deposit paid
- September 19: The card arrived and I activated it
- Mid-October: A pre-qualified letter came from Capital One
- October 17: Approved for the Capital One Platinum card, $500 limit (3.5 months after arriving)
Step 1: The first application, rejected in seconds
As soon as my Social Security number arrived, I applied for a regular credit card at Capital One, one of the biggest card banks in the US.
I was rejected right away. No phone call, no questions, no chance to explain. The reason was simple: I had no credit history. Their system looked for a credit file with my name on it, found nothing, and said no.
It felt bad. But it is normal. Most new immigrants hit this wall. It is not about you. There is just no data yet.
One thing I learned later: every real application can create a hard inquiry on your credit report. Too many of them in a short time can hurt a new file. So do not apply to five banks in one week hoping one says yes.
Step 2: A secured card
The way around the wall is a secured credit card. You give the bank a deposit, and that deposit becomes your credit limit. If you do not pay, they keep the deposit. So the bank takes almost no risk, and they can say yes to people with no history.
I applied for an OpenSky secured card and chose a $750 deposit. That meant a $750 credit limit.
OpenSky does not check your credit to approve you. But it does check your identity, carefully.
Uploading my passport and SSN three times
After I applied, they asked me to upload my passport and my Social Security card to confirm who I am. I uploaded them. They asked again. I uploaded them again. They asked a third time.
The third time, the account was approved.
I do not know exactly why it took three tries. My guess is the photo quality or a name mismatch between the documents. If this happens to you:
- Take the photo in good light, flat on a table, with all four corners visible.
- No glare, no blur, no fingers covering anything.
- Make sure the name you typed in the application matches the documents exactly.
- Do not give up after the first request. It worked for me on the third.
The card arrives
My card arrived on September 19. A real US credit card, with my name on it. A small thing, but after months of having nothing in my own name, it felt big.
How I use it
A secured card only helps if you use it the right way. The goal is not to borrow money. The goal is to build a record that shows you pay on time.
- I use it for small things I would buy anyway.
- I pay the full balance every month, on time. Never late.
- I keep the balance low compared to the limit. A common rule is to use less than 30% of your limit. On $750, that is under about $225.
The bank reports this to the three credit bureaus (Equifax, Experian and TransUnion) every month. That report is what creates your credit file.
A month later: a letter from the bank that rejected me
About a month after my secured card arrived, a letter came to my house. It was from Capital One, the same bank that had rejected me in seconds.
It was a pre-qualified offer for their Platinum card, with no annual fee.
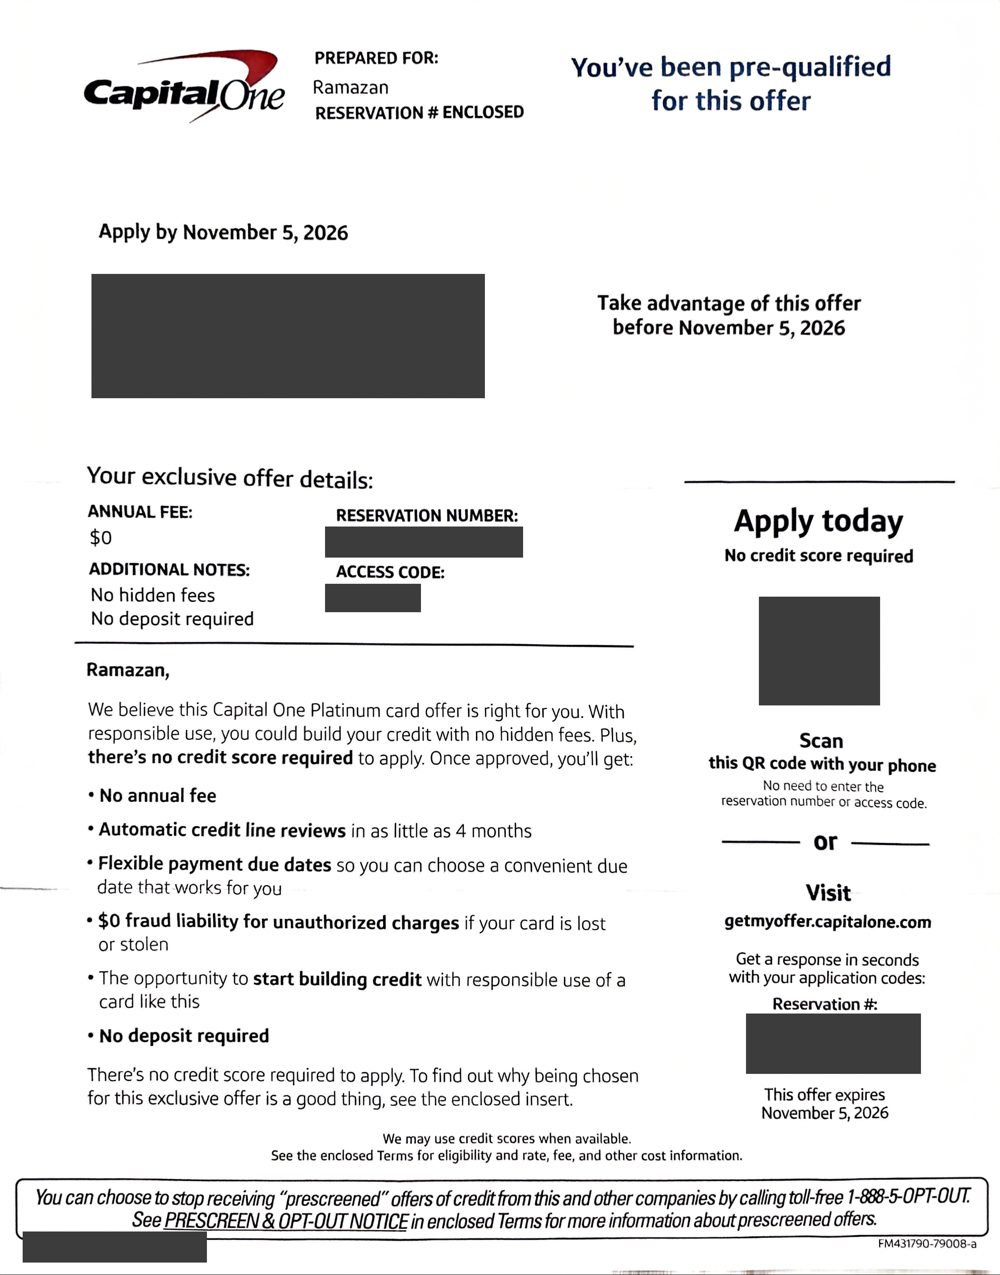
Nothing about me had changed, except one thing: now there was a credit file with my name on it, and it showed one card paid on time. That was enough to move me from "rejected without a question" to "we would like you as a customer".
Pre-qualified is not approved
A pre-qualified offer means the bank looked at a basic version of your file and you passed their first filter. It is a good sign, and the chances are high. But it is not a final approval. When you actually apply, they do a full check.
First, I checked that the letter was real. Scam letters that look like card offers exist, so I did not use anything printed on it. I went to the bank's official website myself and confirmed the offer there.
Then I applied. Approved, with a $500 limit and no annual fee. The same bank that had rejected me without a single question, less than two months earlier.
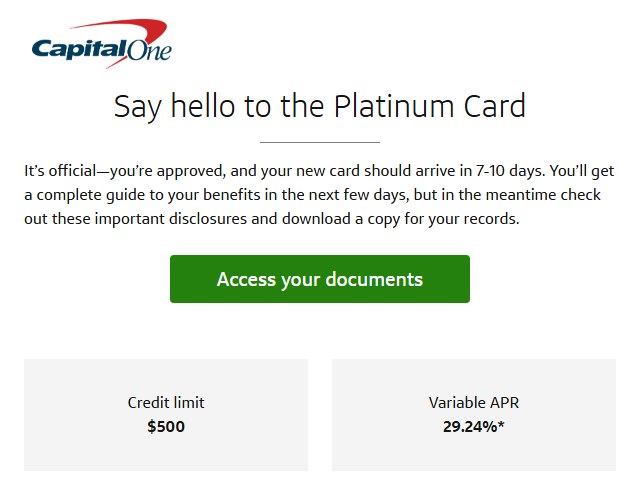
The email also shows the interest rate: 29.24% APR. That is very high. It is one more reason to pay the full balance every month, so that the rate never matters.
Many big card banks also have a pre-approval check on their website. It does not hurt your credit. If I could go back, I would have used that tool before my first application, instead of applying blind and getting rejected.
What I would tell a new immigrant
- Get your SSN first. Most card applications need it. Some banks accept an ITIN.
- Do not start with a regular card. With no history, you will probably be rejected. Start with a secured card.
- Check pre-approval online before any real application. It does not hurt your credit.
- Be patient with identity checks. Clear photos, matching names, and try again.
- Pay in full, every month. This is the whole game.
- Keep the balance low. Under 30% of the limit.
- Wait a month or two. Offers start coming as soon as there is something in your file.
Summary
- No credit history meant an instant rejection from a big bank.
- An OpenSky secured card with a $750 deposit approved me without a credit check, after three rounds of document uploads.
- The card arrived on September 19. I pay it in full every month.
- About a month later, the bank that rejected me mailed me a pre-qualified offer. I applied and got a $500 limit with no annual fee.
The first step is the hardest. After that, the system starts to work for you instead of against you.
If you are still at the step before this, opening a bank account with nothing in your name, I wrote about that here: Opening a personal bank account as a new immigrant.
What I do now to turn these cards into a good score: Building a credit score from zero as an immigrant.
Going through the same thing? If you are stuck on this step and need help, send me a message. I read every one.
Write to me or use another email app
I am not a lawyer or an accountant. This is my own experience, written down as it happened. Rules change and every case is different, so check with the official source or a professional.